15
min read
 Nov 12, 2026
Best fintech UX design agencies for financial products in 2026
Hiring a fintech UX design agency in 2026 is harder than it should be. The same ten or so names appear on every article in the category, most of which are written by agencies ranking themselves. What those articles miss is the real buyer question: how these ten agencies differ from each other, and which kind of product each one is genuinely built for.
I’m Marc Caposino, CEO of Fuselab Creative, one of those agencies. This article is what I would want to find if I were on the buyer’s side of the table. It includes the three questions I would ask in a first sales call, honest takes on each of the ten agencies worth your shortlist, and what the pricing numbers actually include.
The sales pitch is always the same. The shipping record is not.
Every fintech UX design agency that pitches you will say the same five things. They understand compliance. They know KYC and AML. They prioritize user trust. They have a research-led process. They work as a true partner, not a vendor. These sentences are so consistent across the industry that they function as noise rather than signal. I see you nodding your head.
The differences between agencies show up somewhere else. They show up in how the team answers unscripted questions about projects they have shipped. They show up in what parts of the work the agency quietly subcontracts. They show up in which clients the agency has lost and why. None of this is in the portfolio deck.
Over the last decade, I have sat through enough vendor pitches to have a short list of questions that separate agencies that have shipped fintech work from those that have redesigned fintech marketing sites. You can ask these in a first meeting, and the answers will tell you more than any case study.
Show me a KYC flow you shipped, and walk me through what happens when verification fails. Every fintech design agency claims KYC experience. Most have only designed the happy path. Real financial products live in the exception states: failed verification, manual review escalation, document mismatch, timeout and re-entry, and cases where the name on a user’s passport does not match the name on their bank account. An agency that has shipped this work talks about failure modes without being prompted. An agency that has not usually changes the subject.
Which part of this project did you not do, and who did it? Fintech engagements often get quietly split. The pitching agency designs the screens. A development partner you have never heard of quietly handles research development. A third shop handles compliance mapping. None of this is disclosed up front. You find out six weeks in when the research deliverable shows up with a different logo on it. When you ask a question like this, a confident agency will tell you exactly what it handles in-house and where it brings in partners, because that answer is a sign of a practice that knows its lane. It’s also an indication that an agency isn’t going to attempt to deceive you down the road when issues arise. In fact, I would go as far as to say an agency that tells you bad news as soon as an issue comes up is a really good sign.
What would you change about your most recent fintech project if you could go back? An agency that has genuinely shipped hard work will answer this. They will tell you about a compliance requirement they caught too late, a design system they underscoped, a user segment they underserved. An agency that has not shipped hard work will tell you what a great client their last fintech was. The absence of regret is, as they say in poker, “the tell”.
Five fintech product types, and what each one actually needs
The single biggest mistake in this market is ranking fintech agencies by overall quality. Quality is not the right axis. A consumer neobank, a regulated bank modernization, a B2B SaaS risk platform, a lending origination system, and an internal financial dashboard are five genuinely different design problems. The agencies that are excellent at one are often wrong for the others. The honest version of this article does not tell you which agency to hire. It tells you what to look for and lets you match it to the shortlist below.
Regulated bank modernization. If you are a bank running a full digital transformation (core banking, mobile app, corporate banking portal, integrated wealth management), the question is not who makes the prettiest screens. It is about who has shipped this specific work at this specific scale before. Look for agencies with five or more shipped banking products, named institutional clients, and a documented methodology for multi-product rollouts. Agencies without a banking institution track record will spend time learning while utilizing your budget.
Consumer neobank or retail payments app. The problem here is brand differentiation and onboarding conversion in a crowded market where incumbent banks have a muscle-memory advantage. Look for agencies with shipped consumer financial products you have actually used yourself, demonstrable brand craft, and an onboarding-optimization track record with measurable conversion outcomes. Agencies that only show back-office or enterprise work do not translate to this brief, regardless of how strong the enterprise work looks.
B2B fintech SaaS. This covers risk platforms, analytics dashboards, compliance tools and embedded finance infrastructure. The design problem is organizing genuine complexity without collapsing it. Look for agencies with deep B2B product experience, multiple shipped products with multi-role permissions, and evidence that their dashboards survive institutional review. My agency, Fuselab Creative, competes directly on the data-heavy end of this category.
Startup MVP on a budget. At this stage, the question is less about which agency is best and more about which engagement model fits your stage. Subscription or embedded-designer agencies are a good fit when you need continuous iteration over a six-month or longer runway rather than a block or deliverable-based engagement. Avoid agencies with exceptionally low bids for this work. You will not get the right attention for your product needs, and information architecture mistakes compound at a high cost over the next 12 months.
Internal financial dashboards and operational tools. This is where Fuselab competes directly. The discipline required (dense data organized by user role, decisions made under time pressure, primary views that do not require training to read, real-time updates that indicate what changed) applies to internal risk dashboards, trade blotters, operations tools, and institutional analytics platforms. These are different design problems from consumer onboarding, and agencies built for consumer work do not translate cleanly.
The ten agencies worth your shortlist, with honest takes
The numbering below is editorial sequence, not quality ranking. Every agency on this list is credible. What differs is what each one is actually good at, where they overreach, and when I would tell a buyer to call someone else.
1. Fuselab Creative
McLean, VA. Hourly rate: $100–$149. Minimum project: $25,000. Clutch rating: 5.0.
Hire us for: Enterprise financial dashboards, institutional data platforms and operational tools where the design problem is information density rather than onboarding psychology.
The representative Fuselab engagement is the kind where a professional user opens the product every day, needs to make decisions quickly, and does not want to be charmed by the interface. The Fiserv Small Business Index is our representative case: an interactive platform that tracks small-business sales across US sectors and states, with monthly data refreshes, three drill-down levels, and a custom visualization library that the Fiserv team extends independently.
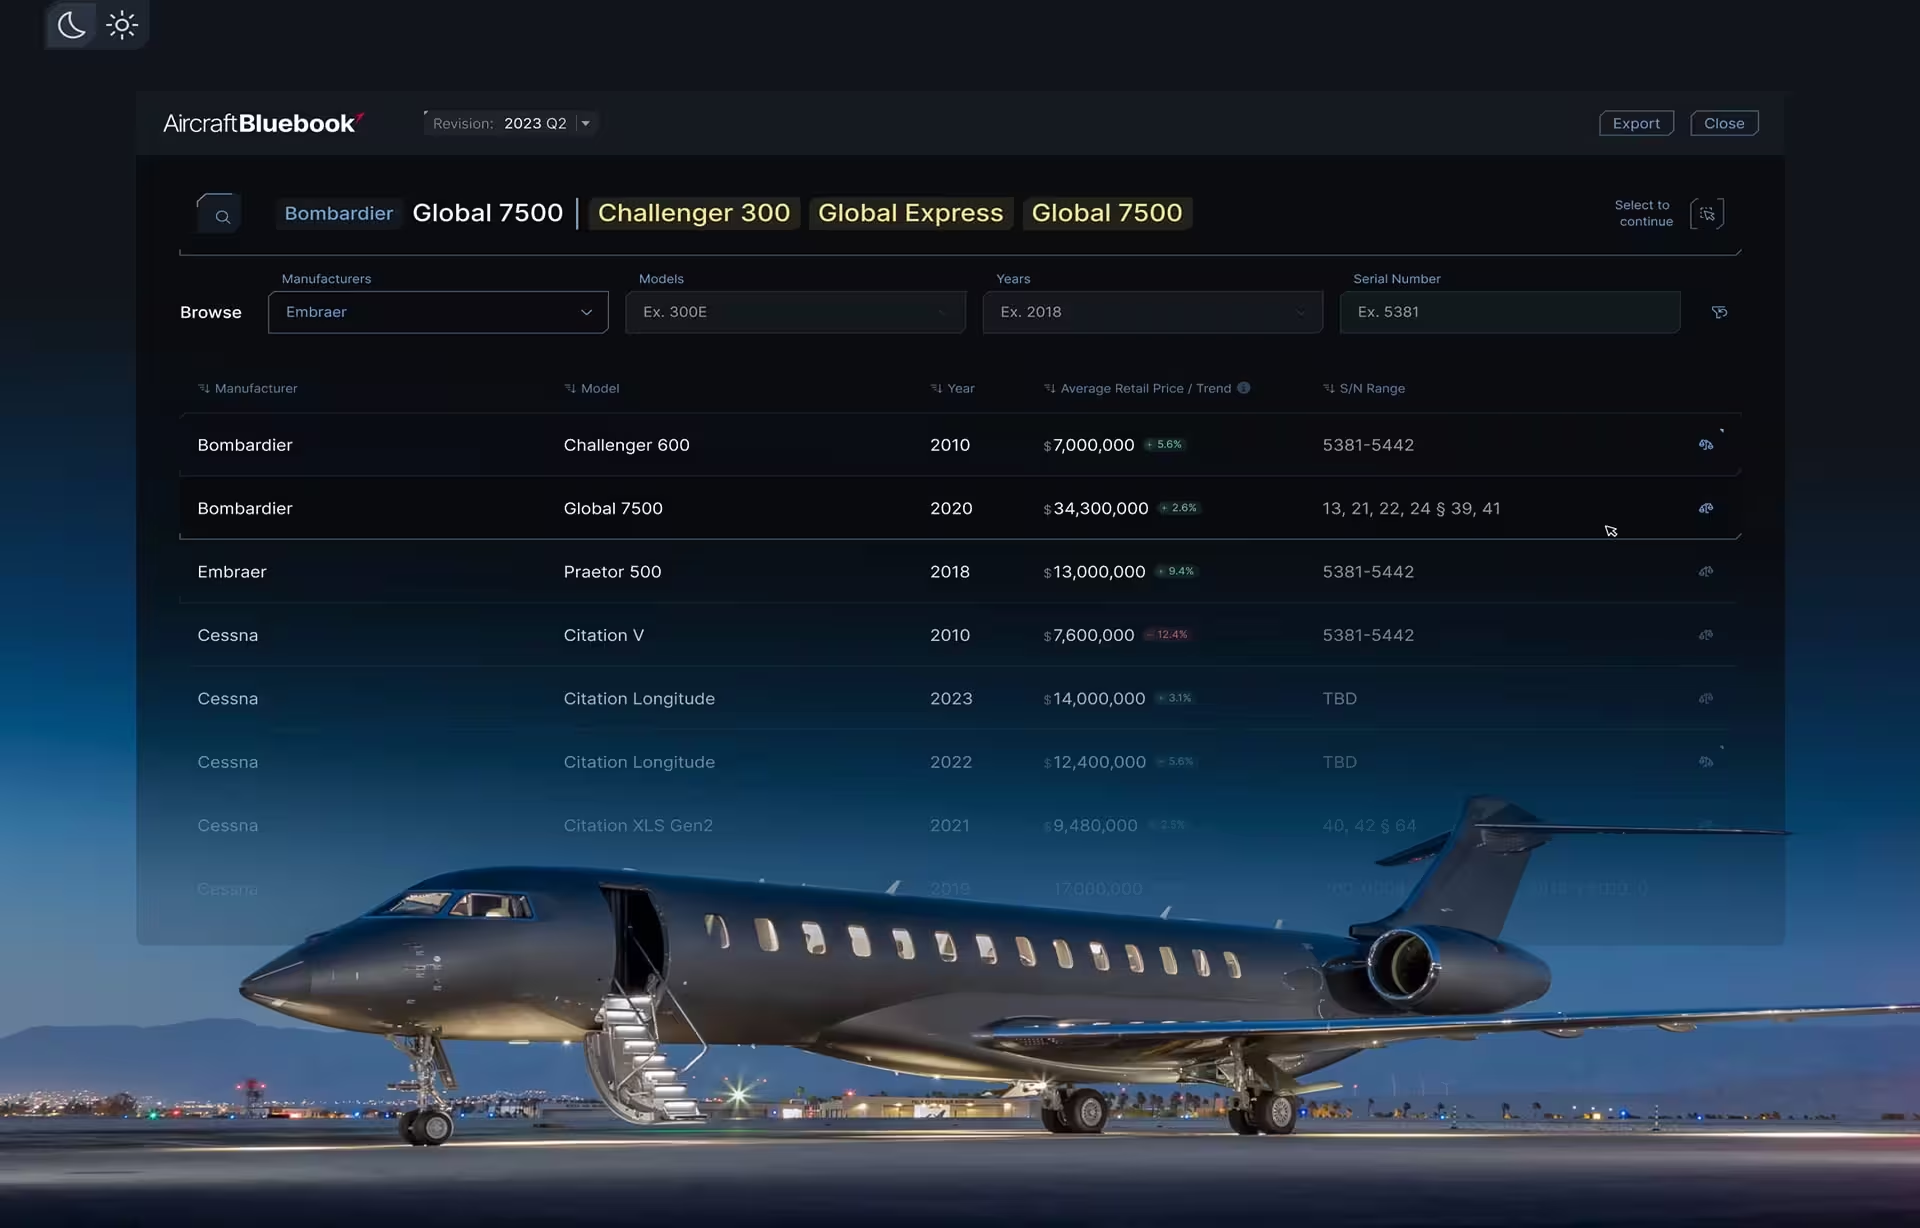
Aircraft Bluebook is a second fintech engagement in the same pattern: the dashboard interface for aircraft valuation data used by finance teams in aviation lending, leasing, and insurance decisions. Enterprise dashboard work for Uber and other institutional clients fills out the portfolio. If this is the shape of your project, we can compete seriously. If it isn’t, the nine agency takes below should help you build a better shortlist instead.
2. Excited
Lviv, Ukraine (also Tallinn). Hourly rate: $50–$99. Minimum project: $10,000. Clutch rating: 5.0.
Excited is a product design studio from Lviv, with a second office in Tallinn, that splits its financial work between consumer banking and insurtech. Its named projects include Me, a family banking app in Bahrain, and two insurtech platforms: Xilo for quoting and sales automation, and InsuredMine for CRM and marketing. It also has Web3 work, including the Verida data wallet.
The team covers research, UX audits, UI design, prototyping, and design systems, plus Webflow builds and branding. It does not build production app code, so a fintech team without its own engineers will need a separate development partner. The $10,000 minimum makes it a practical first engagement for a seed-stage product.
3. UXDA
Riga, Latvia. Hourly rate: $200–$300. Minimum project: $250,000. Clutch rating: 4.6.
UXDA is the only agency on this list that works exclusively in finance. The portfolio is 150-plus banking and fintech products across 39 countries. The client list includes HSBC, Emirates NBD, Garanti BBVA, Bank of Jordan, Finastra, Backbase, GCash, SurePrep by Thomson Reuters, Magma, and Private Wealth Systems. UXDA accepts a small number of institutional engagements per year and will politely decline work that does not fit.
The $250,000 minimum is the right filter on both sides. If your project is below that, UXDA is not for you, and that is not a judgment on your project; it is how their practice is structured. If your project is above that and you are a bank or a serious fintech, no agency on this list has done this work more times.
4. Momentum Design Lab
San Mateo, CA (with NYC and London). Hourly rate: $150–$199. Minimum project: $25,000. Clutch rating: 4.6.
Momentum is the enterprise-transformation shop. Fortune 500 banks, wealth management firms and CRM analytics platforms. HTEC Group acquired Momentum in 2021, adding engineering capacity that most design-only agencies cannot match, and the combination matters when the deliverable must survive a CIO review.
The sweet spot is large data architectures meeting role-based interfaces: analysts, advisors, and executives looking at the same data with different default views. It is not the right shape for a fintech startup that needs iteration velocity at an offshore price point, and the engagement model is honest about it.
5. Groto
Delhi, India. Hourly rate: $50–$99. Minimum project: $5,000. Clutch rating: 4.9.
Groto is a Delhi product design studio founded in 2021, the youngest on this list, and its sharpest skill is interfaces for AI products: chatbots, agents, and data dashboards. Its fintech portfolio is thinner than its AI work. The clearest example is STBL, an investment app for a bullion-backed startup, alongside SaaS and health products such as Barista and Gini.
That mix suits a fintech team adding an AI assistant, a conversational onboarding flow, or an analytics dashboard to an existing product. A bank or lender with heavy compliance requirements should ask to see regulated financial work first, because the published portfolio does not show it. Fixed projects start at $5,000.
6. Onething Design
Gurugram, India. Hourly rate: $25–$49. Minimum project: $10,000. Clutch rating: 4.6.
Onething runs a dedicated BFSI track for consumer fintech products in India and Southeast Asia. 35-plus BFSI clients, including HDFC, RBL Bank, and Capri Loans. A research practice that is deeper than the price point suggests, particularly around consumer financial behavior in emerging markets.
The agency is less well-suited to enterprise financial platforms or institutional tools, where the primary problem is data density rather than consumer onboarding. For an Indian neobank or a Southeast Asian payments app, Onething’s regional depth is the differentiator. For a US institutional analytics platform, it is the wrong brief.
7. UX Studio
Budapest, Hungary (US LLC registered). Hourly rate: $50–$99. Minimum project: $10,000. Clutch rating: 4.8.
UX Studio is the research-first pick for fintech products with multiple user roles. Advisor, operations analyst, compliance officer and end customer, each looking at the same data differently. That is the design problem UX Studio is built for, and the portfolio (Finshape, Zignaly, fintech-adjacent work for Cisco) reflects it.
The subscription model for embedded teams gives product organizations real flexibility in engagement structure. The usual offshore caveat applies for work that requires a US presence or on-site compliance workshops. For B2B vertical SaaS in financial services, UX Studio’s multi-role ecosystem experience is the specific strength to weigh.
8. Cieden
Ivano-Frankivsk, Ukraine (also Toronto-registered). Hourly rate: $50–$80. Subscription pricing from around $7,200 per month. Clutch rating: 4.8.
Cieden has built a practice around B2B products where complexity is the defining challenge. AI interfaces, compliance platforms and fintech dashboards that must be readable without collapsing the professional depth users need. The distributed team across seven countries embeds into US product squads, which gives more scheduling flexibility than a pure offshore model.
For data-heavy financial platforms where the core design problem is organizing dense information for non-technical users, Cieden’s B2B data experience transfers directly. Mastercard and Lendflow engagements are representative. This is a genuine specialist at a mid-market price point, which is a rare combination.
9. Qubstudio
Lviv, Ukraine. Hourly rate: $25–$49. Minimum project: $10,000. Clutch rating: 4.9.
Qubstudio has operated since 2006 and has held a spot on Clutch’s top UX lists every year since 2017, a long, uninterrupted run. The financial work spans banking (Gulf Bank, Loan Mantra, Ila Bank, Ozone API, Deaglo), payments, and SaaS fintech. The portfolio is strongest in information architecture and structural organization rather than surface visual design, which is actually what you want at the stage Qubstudio serves best.
For mid-market fintech companies whose product structure will need to grow through three or four feature waves, Qubstudio’s IA depth is the specific skill that saves you from an expensive rebuild at each stage. For founders who want structured UX without enterprise-agency overhead, this is the right price-to-depth trade in the category.
10. Humbleteam
Prague, Czech Republic (also Dubai). Hourly rate: $50–$99. Minimum project: $5,000. Clutch rating: 4.9.
Humbleteam is a Prague product design studio with a second office in Dubai, and financial services is its largest sector on Clutch. Its named fintech work includes the design system and web app for DailyPay, an earned wage access company, a rebrand and full redesign of NayaPay’s MENA wallet, and ongoing product design for the Hyperliquid exchange. Outside finance, it has designed for Calm, Logitech, and Rimac.
The studio treats product interface and brand as one job, which suits consumer wallets and trading apps where trust has to show on every screen. Teams building back-office or compliance-heavy banking systems should ask how much of that work it has shipped.
The pricing question that never gets asked
Most fintech UX design agency articles on the web mention pricing somewhere, usually as a wave at ranges. Almost none explain what drives the difference between a $10,000 minimum and a $250,000 minimum. The answer is not mainly offshore versus domestic. The answer is what the number includes.
A $10,000 minimum usually buys design iteration on screens you have already scoped, usually across six to eight weeks. A $50,000 minimum buys design, some research and a small design system, usually over three to four months. A $250,000 minimum buys a full UX strategy practice, institutional-grade research, a governed design system, compliance mapping integrated into the interaction design, and the time required to get legal and risk teams aligned before wireframing begins, usually across six to nine months. These are different products sold under the same label.
The pricing question you should actually ask is: What does the engagement include, what does it explicitly exclude, and what will I need to buy separately from a different vendor to ship the product? Pin the agency down on that in the first conversation. Otherwise, you will find out in month three that the $50,000 quote did not include research, the design system was scoped at half what the product needed, and the budget has to stretch to cover both.
Fintech UX design agency comparison table
One more thing worth saying about trust
Most articles in this category will tell you that fintech UX is about trust. That is true, and it is also the most useless sentence you can read on the topic. Everything is about trust in fintech, which means the word does no work on its own.
The specific version of trust that matters in fintech UX is narrower: users judge a financial product’s credibility in the first second of contact, mostly from visual cues they cannot consciously name. Baymard Institute’s research on perceived checkout security documents this directly. Users evaluate payment forms based on visual cues for the credit card fields, not on the underlying technical security. Background colors, site seals, padlock icons, and brand presentation do more work than any backend guarantee the user will never see.
The corollary is Nielsen Norman Group’s hierarchy of trust: users must clear low-commitment interactions before they accept high-commitment ones like entering payment details or authorizing a recurring charge. Fintech onboarding flows that ask for sensitive information before the product has demonstrated value break that sequence and bleed users before activation. Designing around this is the first thing a team learns on a shipped fintech project, and it is the last thing a team that has not shipped one thinks to do.
The honest close
Fintech UX is a small specialist market where most serious work goes to the same ten agencies. Your job as a buyer is not to find the best one overall. It is to figure out which of them fits the specific product you are building, and then to ask the three questions in the sales call that separate those who have shipped from those who have not.
If you are building an enterprise financial platform or an institutional data tool, Fuselab’s fintech UX design work is a genuine fit. If you are building something else, the nine other agencies in this article include the right answer for your brief, and the honest takes on each one should help you narrow the shortlist and then make the call yourself.
Frequently asked questions
How much does fintech UX design cost in 2026?
A project with a US-based banking UX agency typically runs $50,000 to $200,000. Offshore engagements with the reputable firms on this list run $15,000 to $60,000. Subscription models for startups start around $7,000 per month for a dedicated designer. Wide range because scope varies: a single KYC flow redesign and a full banking platform transformation are not the same project at all.
How do I evaluate a fintech UX design agency before signing?
Ask for a walkthrough of a shipped KYC flow, including the failed-verification state. Ask which parts of the engagement get subcontracted and to whom. Ask what the agency would change about their most recent fintech project if they could go back. The three answers together will tell you more than any portfolio deck.
Should I hire an offshore fintech design agency or a US-based one?
Most offshore fintech design agencies on this list charge $25 to $99 per hour and are genuinely strong at product design, research, and design systems. US-based agencies cost more and usually justify the difference when a project needs in-person workshops, on-site user research, or close work with domestic legal and compliance teams. Match the engagement model to the project rather than to the price: async collaboration suits a well-scoped product team, while a regulated launch with many stakeholders benefits from a partner in your time zone.
What should a fintech UX design portfolio demonstrate?
Shipped products with named financial clients, not concept work. KYC and onboarding flows that include failure states and manual review paths, not just the happy path. Real data density in the dashboard works. Case studies that explain how specific regulatory constraints changed the design, because that is the strongest signal an agency has actually done the work rather than observed it from across the room.
What compliance requirements affect financial UX design?
Financial UX design must account for KYC and AML flows that verify user identity, PCI-DSS governing payment data handling, and SOC 2 covering organizational security controls. In Europe, MiFID II dictates how investment product information is presented, and GDPR governs how financial data is stored and displayed within the interface. Compliance is the floor of the design work, not the ceiling, and the difference between the two is visible in the work an agency produces.